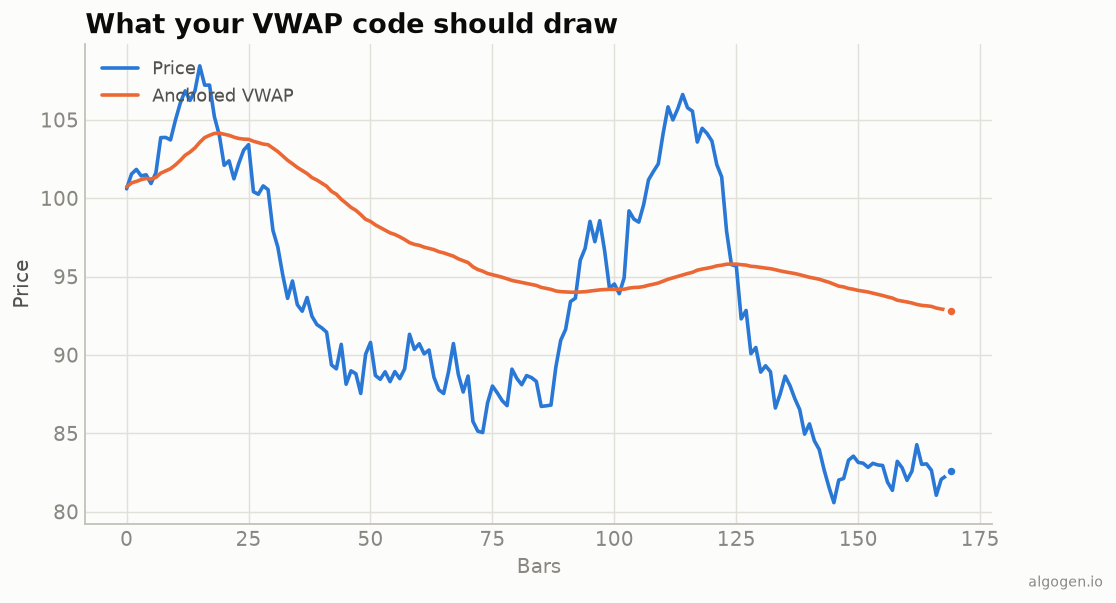
VWAP in NinjaTrader — NinjaScript (C#) Source
A session VWAP that resets each trading day for NinjaTrader 8
Read post →Blog / page 7
Historical validation research, market mechanics, and tooling from the Algogen team.
A session VWAP that resets each trading day for NinjaTrader 8
Read post → A session VWAP that resets each day for MT5
Read post → The built-in ta.vwap, bands, and an anchored version
Read post →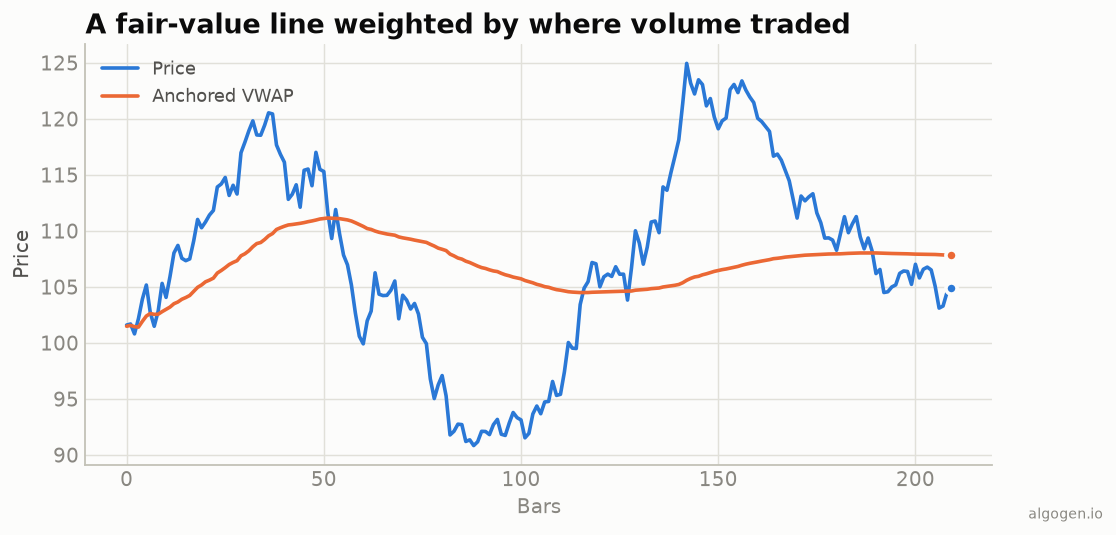
How a 1980s institutional benchmark became everyone's fair-value line
Read post → Session VWAP with a daily reset, and anchored VWAP
Read post →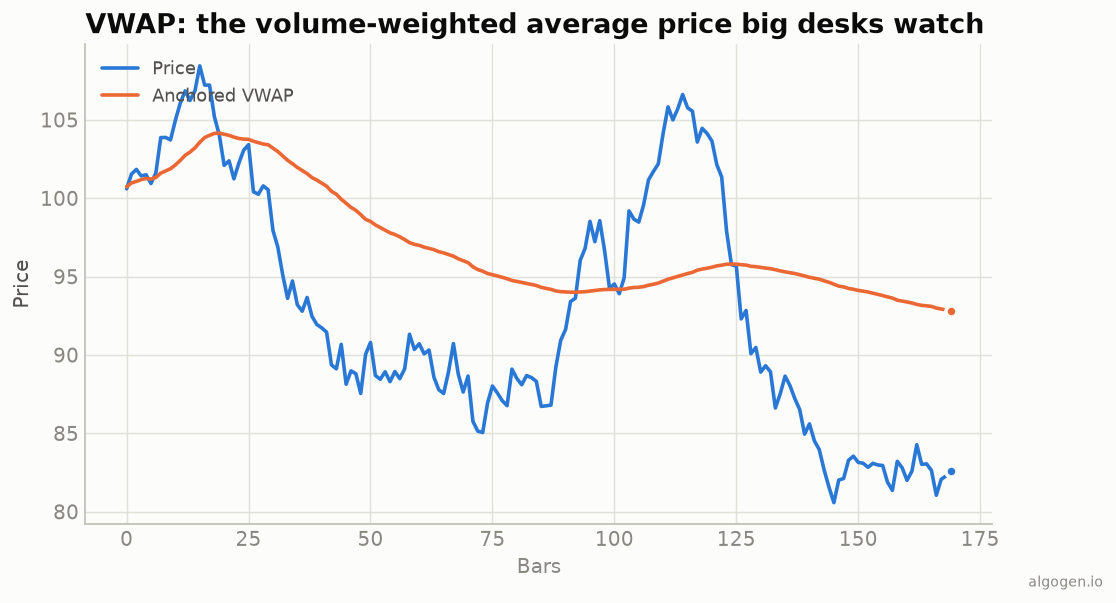
Volume-weighted average price, session vs anchored, and how to read it
Read post →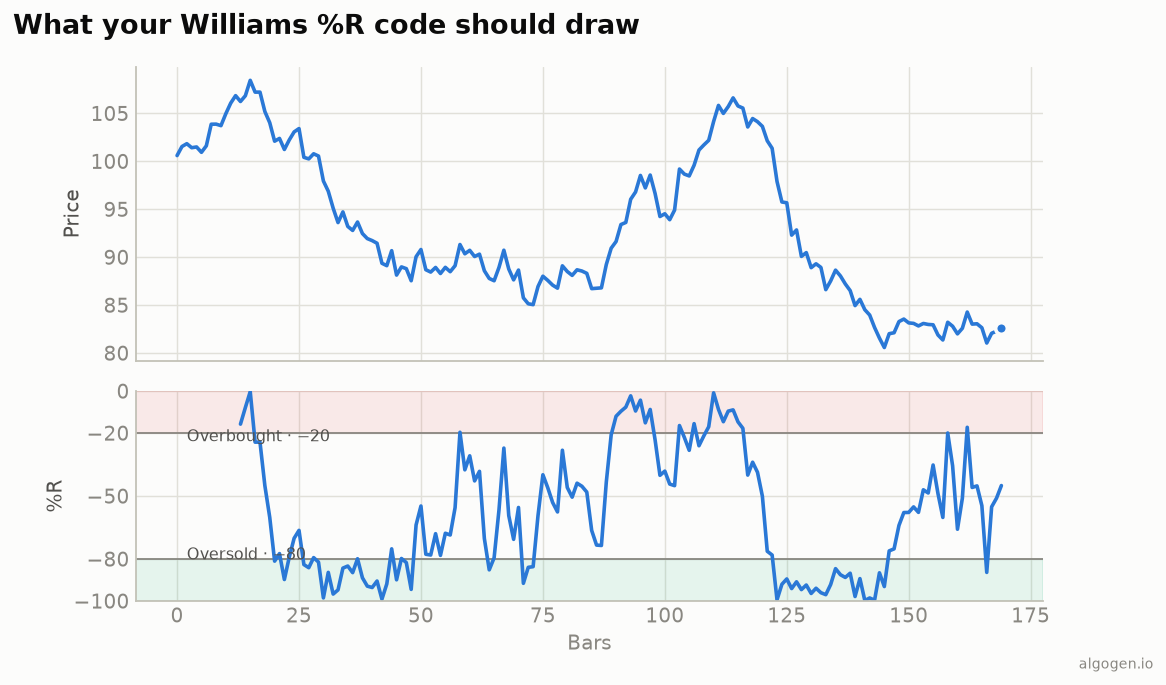
The built-in function and a from-scratch %R
Read post → A custom Williams %R oscillator for NinjaTrader 8
Read post → A custom Williams %R oscillator for MT5
Read post → The built-in ta.wpr and a smoothed variant
Read post →
The 1966 indicator, the 1987 World Cup, and a very public career
Read post → The formula, the divide-by-zero guard, and the stochastic link
Read post →