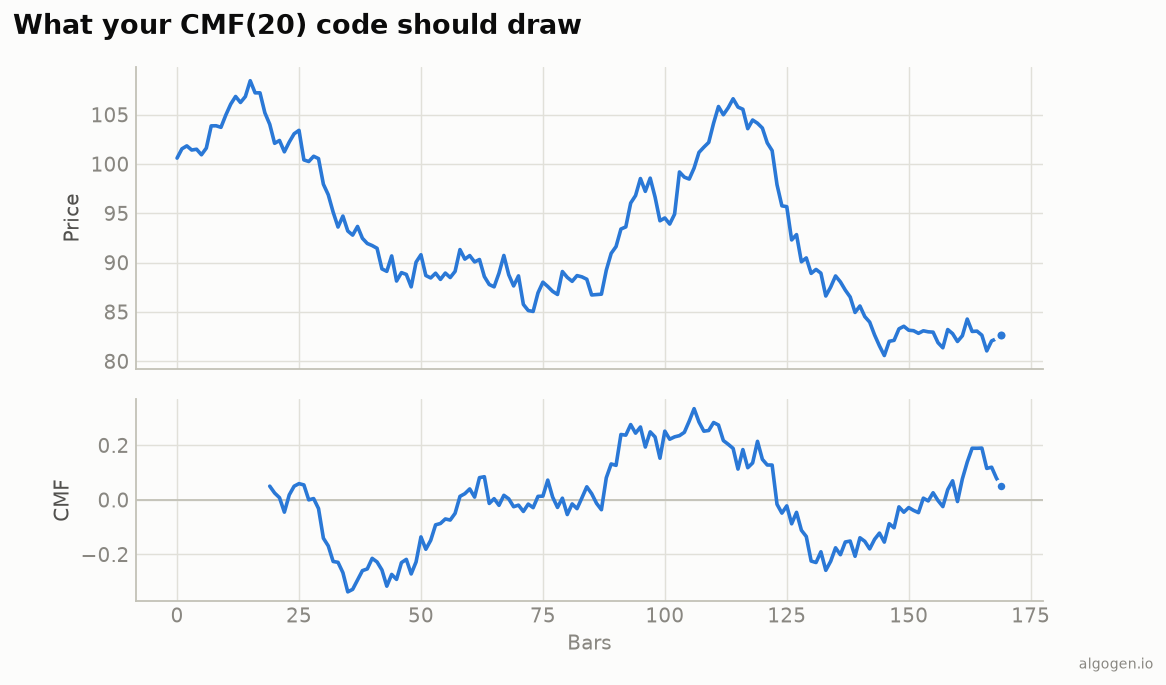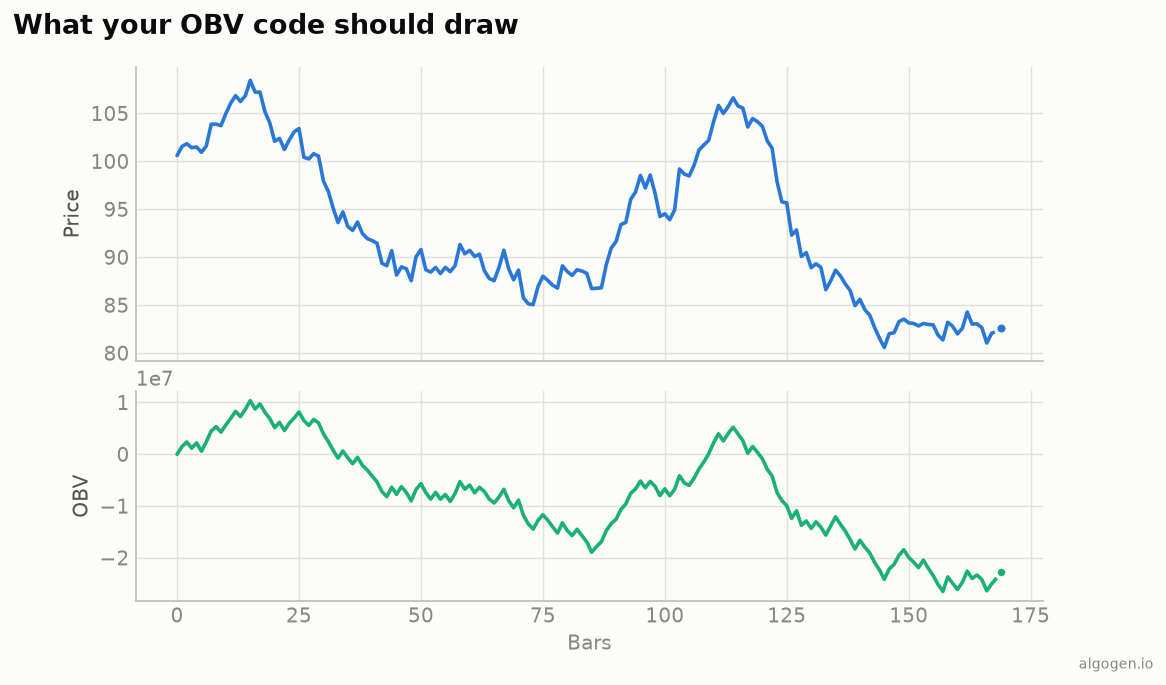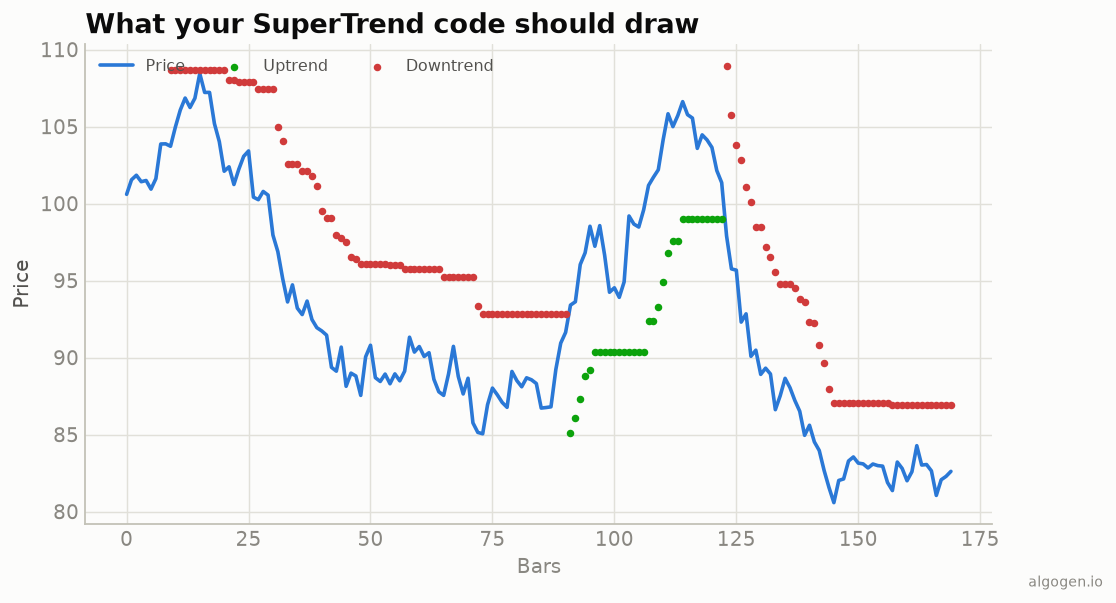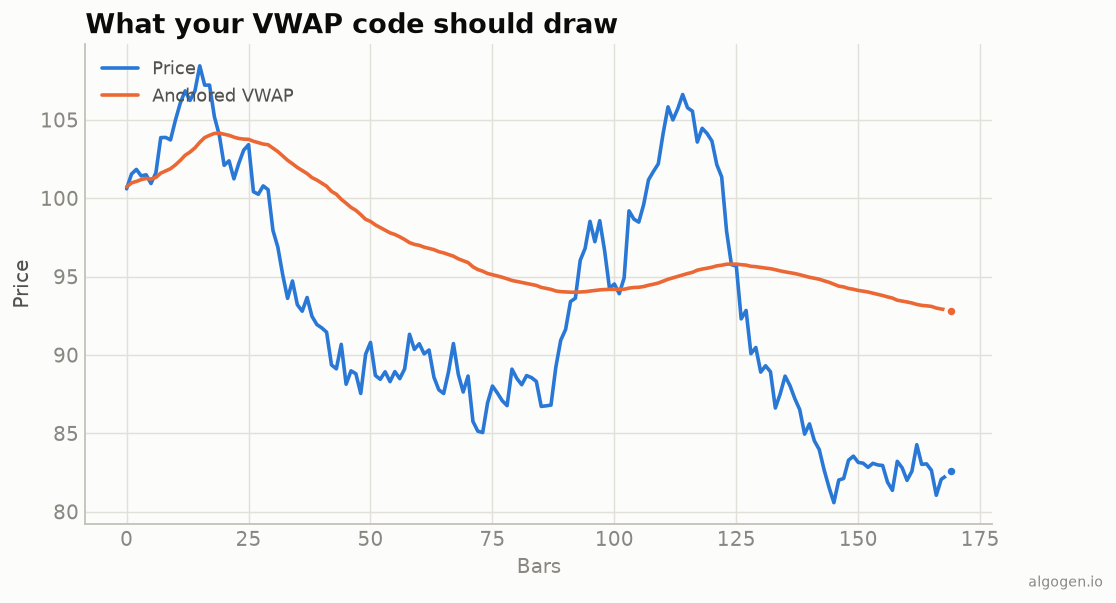
MetaTrader doesn’t ship a session VWAP by default, so this is a genuinely useful one to build. The key mechanic is resetting the accumulation at each new trading day. See the explainer for the concept.
What you’ll need
- MetaTrader 5 with MetaEditor
- Save as
AlgoGen.VWAP.mq5underMQL5/Indicators/
The source
//+------------------------------------------------------------------+
//|                                                 AlgoGen.VWAP.mq5 |
//|                                          Copyright 2026, AlgoGen |
//|                                           https://www.algogen.io |
//+------------------------------------------------------------------+
#property copyright "Copyright 2026, AlgoGen"
#property link      "https://www.algogen.io"
#property version   "1.00"
#property indicator_chart_window
#property indicator_buffers 1
#property indicator_plots   1

#property indicator_label1  "VWAP"
#property indicator_type1   DRAW_LINE
#property indicator_color1  clrOrangeRed
#property indicator_width1  2

input bool InpUseRealVolume = true; // Real volume (else tick volume)

double VWAPBuffer[];

int OnInit()
  {
   SetIndexBuffer(0, VWAPBuffer, INDICATOR_DATA);
   IndicatorSetString(INDICATOR_SHORTNAME, "AlgoGen VWAP (session)");
   return(INIT_SUCCEEDED);
  }

// Return the calendar day (midnight) for a bar time.
datetime DayOf(datetime t)
  {
   return(t - (t % 86400));
  }

int OnCalculate(const int rates_total, const int prev_calculated,
                const datetime &time[], const double &open[],
                const double &high[],   const double &low[],
                const double &close[],  const long &tick_volume[],
                const long &volume[],   const int &spread[])
  {
   int start = (prev_calculated > 0) ? prev_calculated - 1 : 0;

   double cumPV = 0.0, cumV = 0.0;
   datetime curDay = 0;

   // Rebuild the running sums from the start of the current bar's day.
   for(int i = start; i < rates_total; i++)
     {
      datetime d = DayOf(time[i]);
      if(d != curDay)                       // new session -> reset
        {
         curDay = d; cumPV = 0.0; cumV = 0.0;
        }
      double typical = (high[i] + low[i] + close[i]) / 3.0;
      double vol = InpUseRealVolume ? (double)volume[i] : (double)tick_volume[i];
      cumPV += typical * vol;
      cumV  += vol;
      VWAPBuffer[i] = (cumV > 0.0) ? cumPV / cumV : typical;
     }
   return(rates_total);
  }
//+------------------------------------------------------------------+
Install & compile
- Drop it in
MQL5/Indicators/, press F7. - Apply to an intraday chart — the VWAP overlays price and resets each day (you’ll see the characteristic new line each session).
Gotchas
- The daily reset.
DayOfstrips the time-of-day so a change of calendar day triggers a reset of the cumulative sums. Without a reset, you’d get an anchored-from-forever line, not a session VWAP. - Incremental recompute caveat. Because this recomputes cumulative sums, the loop must restart from the beginning of the current session; for production, cache per-session sums rather than the simplified full-rebuild shown here.
- Volume source. Real volume is ideal; on many FX feeds you only have tick
volume, which makes VWAP a rough proxy. Set
InpUseRealVolumeaccordingly.
Same indicator elsewhere: Python, Pine Script, EasyLanguage, NinjaScript. Then test a VWAP rule in AlgoGen.
This post is educational, not financial advice. Indicators describe the past; they don’t predict the future. Backtest anything before you risk real money on it.
Sources and further reading
- The Total Cost of Transactions on the NYSE (The Journal of Finance)
- Technical indicator functions (MetaQuotes)